REVERSE MORTGAGE SPECIALISTS · VICTORIA

Senior Australians guided

All Aus.

Reverse Mortgages Victoria was built on a simple belief: that Australians approaching retirement deserve honest, expert, face-to-face advice from someone who genuinely understands their situation - not a call centre, not a sales script, and not a one-size-fits-all product.

Since 2002, that belief has guided everything we do.

Income Stream


1999

Paul begins his career in the mortgage industry.

2002

Reverse mortgages become his sole focus.

Today

A small, dedicated team — and one of the most experienced specialist brokerages in Australia.

Using Your Home Equity as an Income Stream

For many retirees, the challenge isn’t a single large expense, it’s the gradual, steady pressure of living costs that aren’t quite covered by a pension or superannuation alone. The gap between what comes in each month and what goes out can quietly erode the quality of life you’ve worked so hard to build.


A reverse mortgage income stream gives you access to regular payments drawn from your home’s equity - on a schedule that suits you, without the need for regular repayments. It’s a way of converting part of the wealth that’s been sitting in your home into the financial breathing room you need to live well.


Paul Dwyer
Founder

30+ years in retirement lending

Accredited and locally based in Victoria.

“If a reverse mortgage isn’t the right solution, we’ll say so. Our obligation is always to the client – not the transaction.”

How an income stream works

Rather than accessing your equity as a single lump sum, an income stream releases funds in regular instalments - monthly, quarterly, or over a defined period. You can choose the amount and frequency that best suits your budget and lifestyle.


The amounts drawn are added to your loan balance over time, along with compounding interest. The total is repaid when the last borrower permanently leaves the property - typically through the sale of the home. You will never owe more than the value of your home.


An income stream can also be combined with a lump sum or a line of credit, depending on your needs. Reverse Mortgages Victoria will help you think through the structure that best fits your situation.

Rather than accessing your equity as a single lump sum, an income stream releases funds in regular instalments - monthly, quarterly, or over a defined period. You can choose the amount and frequency that best suits your budget and lifestyle.


The amounts drawn are added to your loan balance over time, along with compounding interest. The total is repaid when the last borrower permanently leaves the property - typically through the sale of the home. You will never owe more than the value of your home.

An income stream can also be combined with a lump sum or a line of credit, depending on your needs. Reverse mortgages victoria will help you think through the structure that best fits your situation.
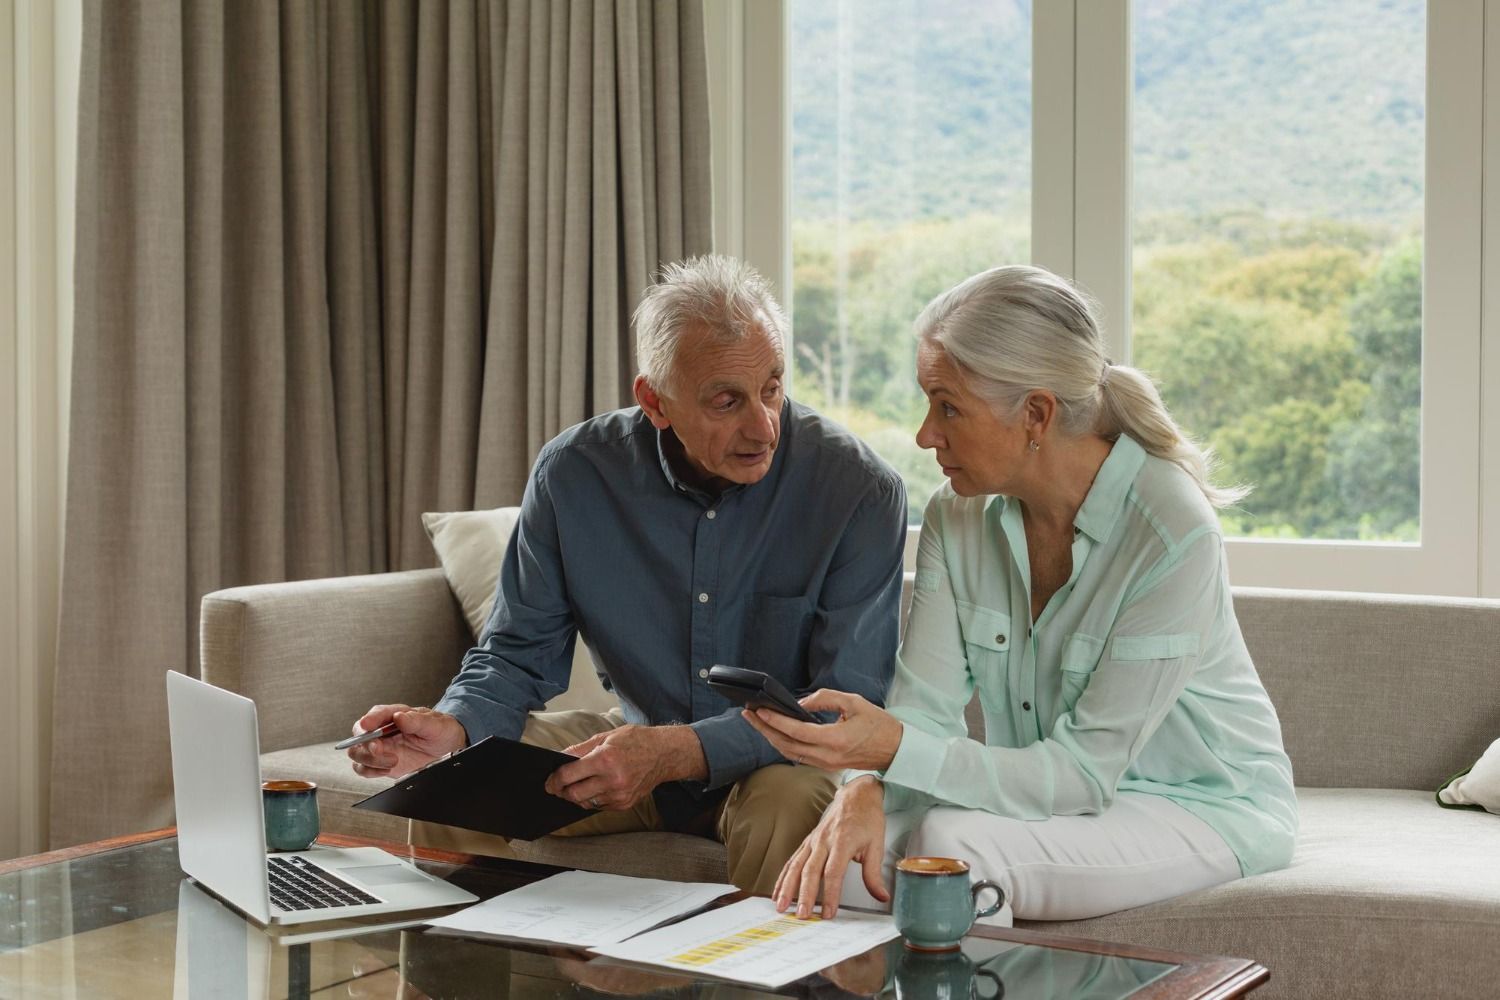
No call centre and no one-size-fits-all approach. Paul or one of his specialist advisers will come to you (within Greater Melbourne region), meeting face-to-face in your own home to find the right path forward, or to tell you honestly if a reverse mortgage isn't it.

What is a reverse mortgage?

No Negative Equity Guarantee

How does a loan facility work for existing borrowers?

Set up a line of credit and draw funds only as you need them, so money is on hand for whenever life calls for it. Covering future or unexpected costs.

Best for:

  • Covering future or unexpected costs
  • Drawing funds at your own pace
  • Reassurance of being able to cover unexpected costs
Learn More

You Remain on Title

Required by law since 2012, this means you'll never owe more than your home is worth when it's sold. Your family will never be left with a debt to repay.

A reverse mortgage doesn't transfer ownership. You stay on the title for the life of the loan, just as you would with a traditional home loan.

Speak to a Expert

What We Believe

After more than two decades in this field, some things have never changed. These are the principles that guide everything we do at Reverse Mortgages Victoria.

Working alongside what you already have

An income stream is rarely the whole picture. It sits alongside your pension and your superannuation, and the point is to make all three last.

Supplementing your Age Pension

The age pension provides a foundation, but for many retirees it doesn’t stretch as far as it once did. A reverse mortgage income stream can work alongside your pension to fill the gap - giving you a more comfortable and consistent monthly income without the need to sell assets or draw down on super earlier than planned.

It’s important to understand that how you access your equity - and how you hold the funds afterwards - can affect your Centrelink entitlements. Paul and the team have specialist knowledge of the Social Security Act and the relevant asset and income test thresholds, and will always model the implications for your pension as part of their service.

Supplementing Superannuation

Superannuation is designed to support retirement, but depending on your balance and drawdown rate, it may not last as long as you’d like - particularly given that Australians are living longer than ever before.

An income stream from your home equity can work in combination with your super, helping to spread your assets more sustainably across a longer retirement. Rather than drawing down super quickly to cover costs, you can pace your drawdown more carefully while your home equity contributes a regular supplement.


Where superannuation strategy is involved, Reverse Mortgages Victoria can refer you to a licensed financial adviser to ensure you receive appropriate, coordinated advice.

Aged pension and income stream considerations

The way a reverse mortgage income stream interacts with the age pension depends on your individual circumstances, including how you receive and hold the funds. Reverse Mortgages Victoria will ensure this is addressed clearly and thoroughly in their advice, with your Centrelink position always front of mind.